Property damage can turn a normal week into a pile of inspections, estimates, photographs, emails, and insurance paperwork. Then another question appears: what’s a public adjuster, and could hiring one actually make the claim easier? A public adjuster is a licensed insurance professional hired by the policyholder—not the insurance company—to assist with preparing, documenting, and negotiating a property insurance claim. In Texas, public insurance adjusters are licensed by the Texas Department of Insurance (TDI).
That distinction matters.
The insurance company has people evaluating the claim from its side. A public adjuster works from yours.
For Flower Mound homeowners and business owners dealing with roof damage, water damage, fire, smoke, hail, wind, or another significant property loss, understanding that difference can help you decide whether you want professional assistance with the claim or would rather manage the process yourself.
So, what’s a public adjuster in practical terms? Let’s break it down.
What’s a Public Adjuster?
A public adjuster is a professional who represents a property owner during an insurance claim.
The public adjuster can inspect damage, review insurance documents, prepare estimates, organize evidence, communicate with the insurance carrier, and negotiate the claim on the policyholder’s behalf. Texas specifically licenses public insurance adjusters to assist insured property owners with claims.
The most important word here is public.
A public adjuster does not work for your insurance company. You hire the adjuster, and the adjuster’s responsibility is to assist you with presenting your claim.
That can be useful because property claims aren’t always as simple as submitting a few photographs and waiting for a check. A significant loss might involve dozens of damaged items, several rooms, roofing components, insulation, drywall, flooring, electrical systems, personal property, and temporary expenses.
Every item needs to be documented properly.
And small omissions can add up.
What Does a Public Adjuster Actually Do?
If you’re searching what’s a public adjuster, you’re probably less interested in the job title than in what that person actually does for you.
The work generally begins with understanding the loss.
Inspecting and Documenting the Damage
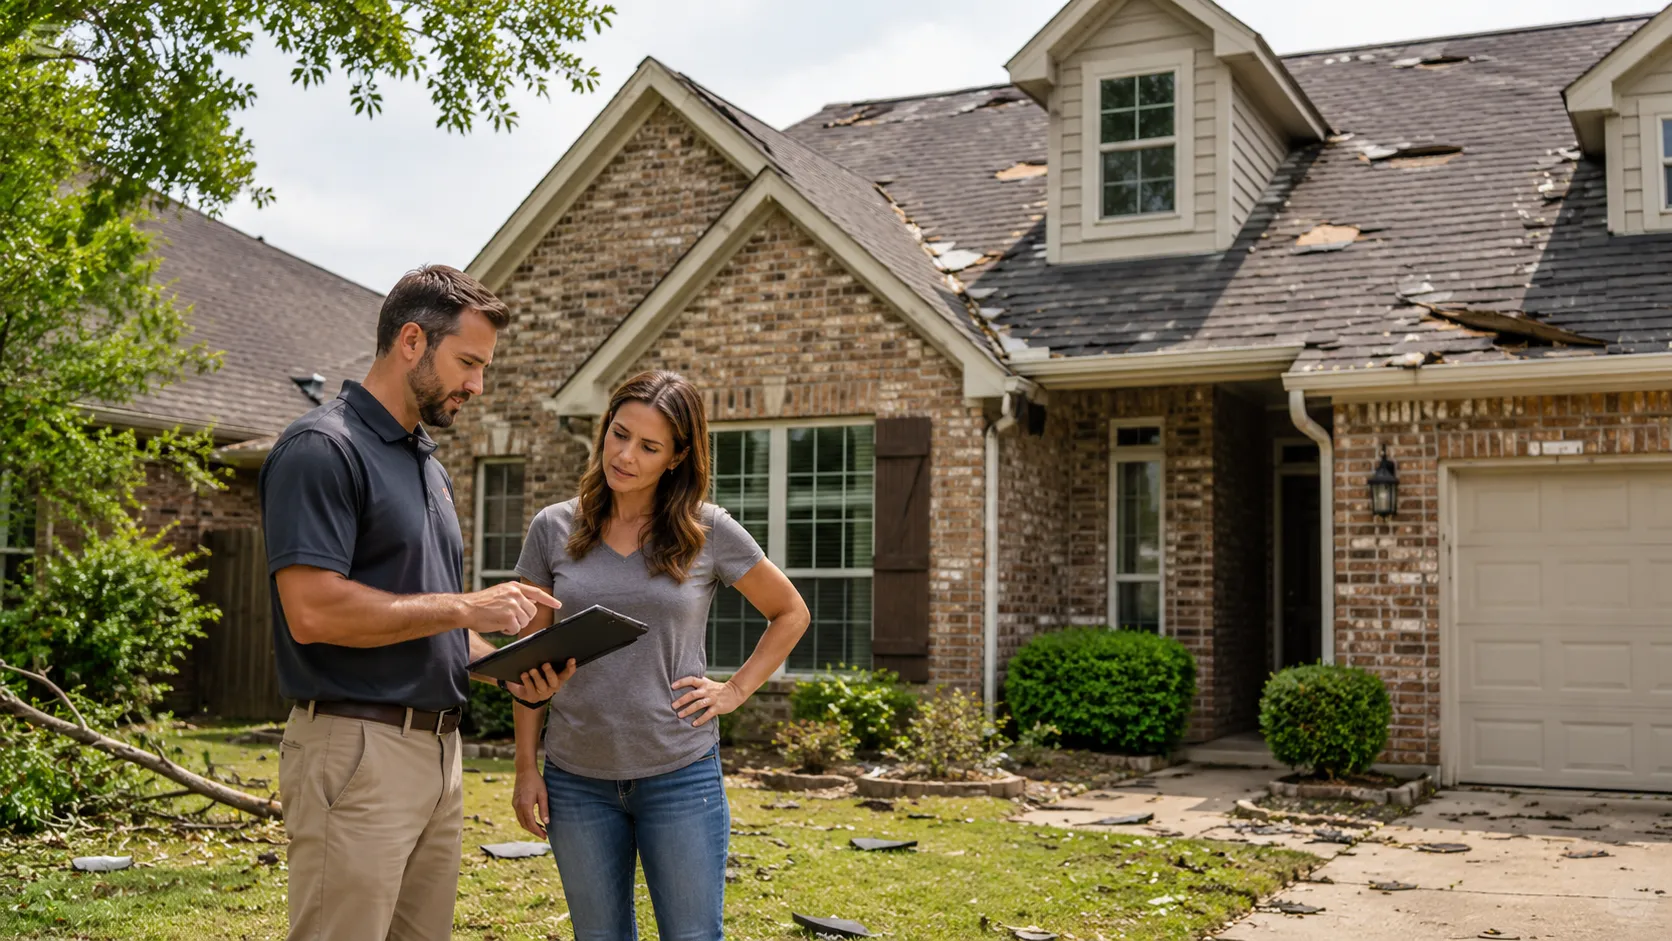
A public adjuster can inspect the property and create a detailed record of damaged areas.
That may include:
- Photographs and videos
- Measurements
- Notes about damaged building materials
- Personal property inventories
- Repair and replacement estimates
- Contractor documentation
- Receipts and invoices
- Evidence of related interior or exterior damage
Consider a storm claim.
The obvious damage might be on the roof, but the complete loss could involve gutters, fencing, siding, windows, interior ceilings, insulation, or water-damaged finishes.
Good claim preparation looks beyond the first visible problem.
It asks a more useful question: What was actually damaged, and what documentation supports it?
Reviewing the Insurance Policy
Insurance policies contain coverage limits, deductibles, endorsements, exclusions, conditions, and other provisions that can affect how a claim is handled.
A public adjuster can review those documents as part of preparing the claim.
That does not mean public adjusters can provide legal advice. Texas rules specifically prohibit them from engaging in the unauthorized practice of law.
Their job is insurance adjusting.
For the property owner, however, simply having someone identify the relevant sections of the policy and connect them to the documented loss can make the claim process much more organized.
Preparing a Detailed Damage Estimate
This is one of the most important parts of a property claim.
A repair estimate needs to answer more than, “The roof is damaged.”
How much roofing needs replacement? What materials are involved? Are gutters affected? Does damaged drywall need removal and replacement? Will matching finishes create additional work? Are there associated labor costs?
Specificity matters.
A public adjuster can prepare or evaluate a detailed estimate and compare it with the insurance company’s estimate to identify differences in the scope or pricing of the documented damage.
Communicating With the Insurance Company
Claims create paperwork.
Lots of it.
There may be inspection appointments, requests for documents, estimate revisions, photographs, proof-of-loss documentation, supplemental information, and questions from the carrier.
A public adjuster can handle much of that claim-related communication.
For busy homeowners or commercial property owners, that alone can be valuable. You’re still responsible for staying informed about your claim, but you don’t necessarily have to personally manage every technical discussion.
Negotiating the Claim
Suppose the insurance company’s estimate includes roof repairs but leaves out documented interior water damage.
Or its estimate covers one damaged area but not another.
A public adjuster can present documentation supporting the additional claimed damage and negotiate with the insurer regarding the scope and value of the loss.
No public adjuster can legitimately guarantee a particular outcome.
But stronger documentation gives the claim a clearer factual foundation.
Public Adjuster vs. Insurance Company Adjuster
Understanding what’s a public adjuster becomes easier when you compare the role with the adjuster sent by your insurance company.
| Public Adjuster | Insurance Company Adjuster |
|---|---|
| Represents the policyholder | Represents the insurance company |
| Hired by the property owner | Assigned or hired by the insurer |
| Reviews damage from the insured’s claim perspective | Evaluates the claim for the carrier |
| Helps prepare and document the claim | Reviews coverage and damages for the insurer |
| Can negotiate with the insurer | Participates in the insurer’s adjustment process |
| Usually paid by the policyholder | Paid by the insurance company |
This doesn’t automatically make the insurance company’s adjuster your opponent.
It simply means the roles are different.
An insurer’s adjuster has responsibilities to the insurance company. A public adjuster’s client is the policyholder.
Public Adjuster vs. Independent Adjuster
Here’s another term that creates confusion.
An independent adjuster sounds like someone who works independently for you.
Usually, that isn’t what the term means.
Independent adjusters are generally outside professionals or adjusting firms hired by insurance companies to evaluate claims on the carrier’s behalf.
A public adjuster is different because the policyholder hires the public adjuster.
So when asking what’s a public adjuster, remember this simple distinction:
Company and independent adjusters work on the insurer’s side of the adjustment process. Public adjusters represent insured policyholders.
When Should You Consider Hiring a Public Adjuster?
Not every insurance claim requires professional representation.
A broken window with a straightforward repair estimate probably doesn’t require the same level of claim management as a major house fire.
But complexity changes things.
You may want to consider speaking with a public adjuster when:
- The property damage is extensive.
- Multiple rooms or building systems are involved.
- You’re struggling to document the complete loss.
- The insurance estimate appears significantly lower than repair estimates.
- Important damage appears to be missing from the carrier’s estimate.
- Your claim requires repeated supplemental documentation.
- The claim is consuming substantial amounts of your time.
- You’re managing a large residential or commercial property loss.
- You want professional assistance communicating with the insurer.
The key word is consider.
Hiring a public adjuster should be a business decision based on the complexity and value of the claim, not an automatic reaction to every property loss.
Claims a Flower Mound Public Adjuster May Handle
Property insurance claims can come from many different types of damage.
A Flower Mound Public Adjuster may assist with claims involving circumstances such as the following.
Hail and Roof Damage
Roof claims can become complicated because damage isn’t always limited to shingles.
Depending on the actual loss, documentation may need to address roofing materials, gutters, vents, flashing, exterior finishes, windows, or interior areas affected by water intrusion.
A detailed inspection can help establish the complete claimed scope.
Wind and Storm Damage
Strong weather can damage roofing, exterior materials, fencing, trees, and other property components.
Water may also enter through storm-created openings.
The challenge is separating unrelated wear from damage associated with the reported event and documenting the claimed loss carefully.
Water Damage
Water moves.
A leak beginning in one location can affect drywall, flooring, insulation, cabinetry, trim, and rooms below or beside the original source.
That makes detailed documentation particularly important.
Fire and Smoke Damage
Fire claims can involve obvious structural destruction plus less visible smoke, soot, odor, and contents damage.
The claim may require inventories, cleaning estimates, demolition costs, reconstruction estimates, and documentation of damaged personal property.
These losses can become complicated quickly.
Commercial Property Damage
Commercial losses may involve building components, equipment, inventory, furniture, tenant improvements, and operational concerns.
When several categories of damage overlap, organized claim documentation becomes even more important.
How the Public Adjusting Process Works
You’ve answered what’s a public adjuster. Now what happens if you actually hire one?
The exact process varies by claim, but it commonly looks something like this:
- Initial consultation: The adjuster reviews the basic facts surrounding your loss and existing claim.
- Contract review: You review the public adjusting agreement, including the fee structure and responsibilities.
- Property inspection: The damage is inspected and documented.
- Policy review: Relevant insurance documents are examined.
- Estimate preparation: The scope and estimated value of documented damage are developed.
- Claim presentation: Supporting information is organized and submitted where appropriate.
- Carrier communication: The adjuster communicates with the insurance company regarding the claim.
- Negotiation: Differences involving documented damage or estimates may be addressed.
- Resolution: The claim continues toward an agreed settlement or another appropriate next step.
Your involvement doesn’t disappear.
You should still read documents, understand important decisions, keep copies of records, and ask questions whenever something is unclear.
How Much Does a Public Adjuster Cost in Texas?
This is an important question.
According to the Texas Department of Insurance, public adjusters in Texas can charge up to 10% of the total amount the insurance company pays for the claim, and the fee can be based on the total settlement rather than only the disputed portion. Texas also requires the fee to be disclosed in the written contract.
That means you should understand the math before signing.
For example, don’t simply ask:
“What percentage do you charge?”
Ask:
- What amount is that percentage applied to?
- When is the fee earned?
- When is payment due?
- What services are included?
- Are there circumstances involving a different fee calculation?
- What cancellation provisions apply?
Texas also has special rules when a claim is settled very quickly after the loss is reported, so the exact contract terms matter.
Read the agreement.
Every page.
Can a Public Adjuster Get You More Money?
Maybe, but that’s the wrong way to frame the decision.
A public adjuster cannot manufacture coverage or turn excluded damage into covered damage.
Nor should anyone promise you a specific settlement.
A better question is:
Could professional documentation and claim preparation help ensure that the full documented loss is properly presented to the insurance company?
That’s where the potential value lies.
For example, an initial estimate might overlook damaged trim, insulation, paint, gutters, flooring, cabinetry, or another component associated with the loss.
If legitimate damage was omitted, better documentation may support a supplemental request.
That’s very different from simply “trying to get more money.”
The objective should be an accurate claim.
Benefits of Hiring a Public Adjuster
For the right claim, professional assistance can offer several practical benefits:
- More detailed damage documentation
- Organized claim records
- Professional repair estimates
- Assistance communicating with the insurer
- Identification of differences between competing estimates
- Help preparing supplemental documentation
- Less time personally spent managing technical claim details
- Representation centered on the policyholder’s documented loss
That last point is significant.
When property damage is substantial, the owner is often dealing simultaneously with contractors, temporary repairs, family needs, business operations, and financial decisions.
Claim administration becomes another job.
Are There Downsides?
Absolutely.
A balanced answer to what’s a public adjuster should also explain why hiring one isn’t automatically the best choice.
First, public adjusters charge a fee.
If your claim is simple and the insurer has already produced an estimate you consider accurate, paying for additional representation may not provide enough value.
Second, experience varies.
A license establishes that someone meets regulatory requirements. It doesn’t automatically tell you whether that person communicates well, understands your particular type of damage, or prepares detailed work.
Third, you are signing a contract.
That contract creates responsibilities.
Read it carefully and understand the fee, scope of services, cancellation terms, and who will actually handle your claim.
How to Choose a Public Adjuster in Flower Mound, TX
Don’t hire based on urgency alone.
Interview the person.
A few good questions can reveal quite a lot:
- Are you currently licensed as a public insurance adjuster in Texas?
- Can I independently verify your license?
- Have you handled claims similar to mine?
- Who will personally inspect my property?
- Who will communicate with the insurance carrier?
- How is your fee calculated?
- What exactly is included in your service?
- How often will I receive updates?
- What happens if we disagree about how the claim should be handled?
- Can I take time to review the contract before signing?
TDI maintains licensing requirements for public insurance adjusters, so verifying credentials should be part of your hiring process.
One more point matters in Texas: public adjusters are restricted from participating directly or indirectly in reconstruction or repair work on property involved in a claim they adjust.
That separation helps avoid conflicts between adjusting the claim and profiting from the repair work.
What Should You Gather Before Meeting With a Public Adjuster?
Preparation helps.
Collect whatever you already have, including:
- Your insurance policy
- Declarations page
- Claim number
- Insurance company estimates
- Letters and emails from the carrier
- Photographs and videos
- Contractor estimates
- Repair invoices
- Emergency mitigation receipts
- Personal property inventories
- Receipts for damaged items when available
- Notes about when and how the damage occurred
Don’t worry if the file isn’t perfect.
The goal is simply to give the adjuster enough information to understand what has happened so far.
Do You Need a Public Adjuster for Every Claim?
No.
That’s worth saying clearly.
You might have a relatively small claim, good documentation, an accurate carrier estimate, and no meaningful disagreement about the damage.
In that situation, hiring additional help may be unnecessary.
But if the claim involves substantial damage, complicated estimates, missing items, repeated negotiations, or an amount large enough that mistakes could become expensive, professional assistance may be worth evaluating.
This is why the answer to what’s a public adjuster shouldn’t end with a sales pitch.
The real question is whether the service solves a problem you actually have.
Why Local Experience Can Matter in Flower Mound
Property construction varies by location, and so do the types of claims adjusters regularly encounter.
Working with someone familiar with homes and commercial properties in Flower Mound and the broader North Texas area can make communication easier, particularly when the claim involves roofing systems, exterior materials, storm damage, water intrusion, or local contractors.
Local familiarity alone isn’t enough, though.
Look for documentation quality, responsiveness, insurance claim experience, licensing, and a clear written agreement.
A Flower Mound Public Adjuster should be able to explain the process in plain English.
If you leave the conversation more confused than when it started, that’s useful information too.
Questions to Ask Before You Sign
Before entering into an agreement, make sure you can answer these questions:
- What will I pay?
- How is that fee calculated?
- What services will the adjuster perform?
- Who will handle my claim?
- How will I receive updates?
- What documents will be prepared?
- How long does the agreement remain in effect?
- What are my cancellation rights?
- How are settlement decisions communicated to me?
Never be embarrassed to ask for an explanation.
It’s your property.
It’s your insurance policy.
And ultimately, it’s your claim.
Frequently Asked Questions About Public Adjusters
1. What’s a public adjuster in simple terms?
A public adjuster is a licensed professional hired by a policyholder to help document, prepare, and negotiate a property insurance claim.
2. Who does a public adjuster represent?
A public adjuster represents the insured property owner rather than the insurance company.
3. Is a public adjuster the same as the insurance company’s adjuster?
No. The insurance company’s adjuster works for or on behalf of the insurer, while a public adjuster is hired by the policyholder.
4. Can a public adjuster inspect roof damage?
Yes. Public adjusters commonly document property damage associated with insurance claims, including claimed roof and exterior damage.
5. Can I hire a public adjuster after I’ve already filed the claim?
Often, yes. Property owners may seek public adjusting assistance after a claim has started, although the circumstances and existing claim status should be reviewed first.
6. Can a public adjuster help with an underpaid claim?
A public adjuster may review the existing estimate and documentation, identify potentially omitted damage, and submit supporting information when appropriate.
7. How much can a public adjuster charge in Texas?
TDI states that a Texas public adjuster’s fee may not exceed 10% of the claim settlement, with additional rules affecting how fees are calculated in certain circumstances.
8. Does hiring a public adjuster guarantee a larger settlement?
No. Claim results depend on the policy, facts of the loss, documentation, coverage, and insurer’s evaluation, and no specific result should be guaranteed.
9. Are public adjusters licensed in Texas?
Yes. Public insurance adjusters are licensed by the Texas Department of Insurance.
10. How do I find a public adjuster in Flower Mound?
Verify the person’s Texas license, ask about experience with your type of property damage, review the fee structure, and make sure you understand the contract before signing.
Is a Public Adjuster Right for Your Claim?
So, what’s a public adjuster?
At its core, a public adjuster is someone you hire to help manage the insurance-adjusting side of a property claim. They can inspect damage, organize evidence, prepare estimates, communicate with the carrier, and negotiate regarding the documented loss.
For a small claim, you may never need one.
For a complicated loss, the equation changes.
When thousands of dollars in repairs, multiple damaged areas, conflicting estimates, or extensive documentation are involved, having someone focused specifically on preparing and presenting the claim can be valuable.
If you’re deciding whether to hire a Flower Mound Public Adjuster, start by reviewing the size and complexity of your loss. Gather your policy, photographs, estimates, and insurer correspondence, then have the claim evaluated before deciding whether professional representation makes sense.
Knowing what’s a public adjuster is the first step.
Knowing whether you actually need one is the decision that matters.